Complete Guide
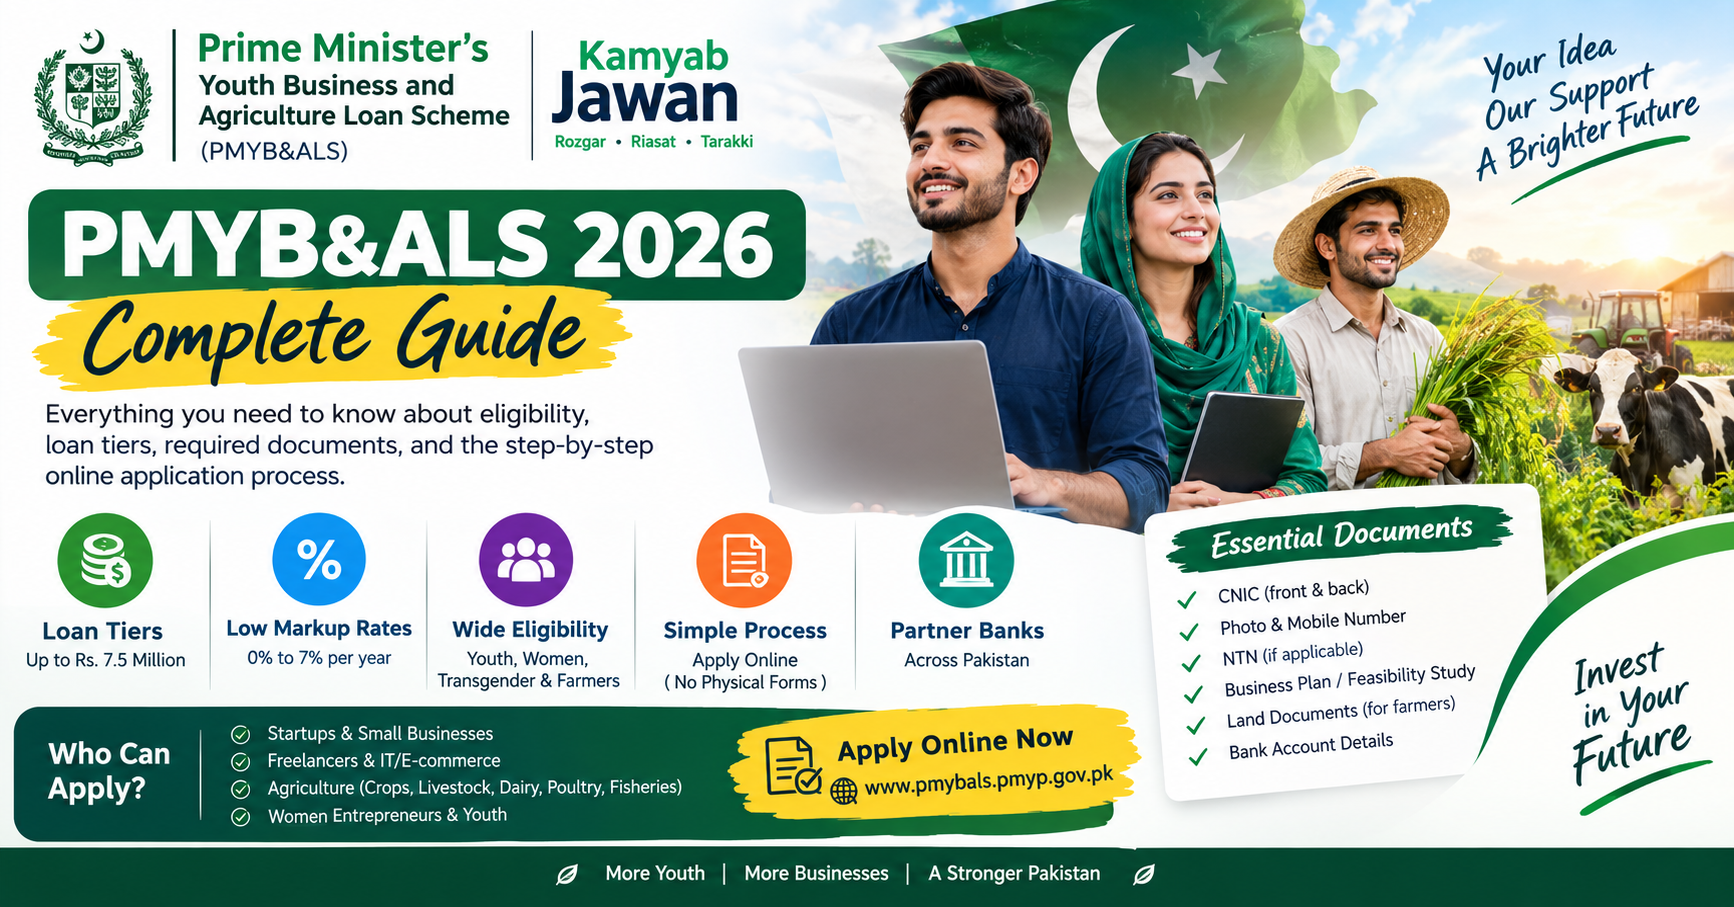
Everything you need to know about eligibility, loan tiers, required documents, and the step-by-step online application process.
Introduction:
Unemployment and lack of access to affordable capital remain two of the biggest barriers young Pakistanis face when trying to start a business or grow a farm. To address this, the Government of Pakistan runs the Prime Minister Youth Business and Agriculture Loan Scheme (PMYB&ALS) often still called by its earlier name, Kamyab Jawan Program under the Prime Minister’s Youth Programme (PMYP).
The scheme offers low-markup and interest-free loans to young entrepreneurs, startups, freelancers, IT/E-commerce founders, women entrepreneurs, and farmers, delivered through a network of partner commercial, Islamic, and microfinance banks across the country. This guide walks through what the scheme is, who qualifies, how much you can borrow, what documents you need, and the exact steps to apply online in 2026.
Important note:
Loan amounts, markup rates, and portal details are set and updated by the government and can change from time to time. Always cross-check the current figures on the official portal, pmybals.pmyp.gov.pk, before applying or making financial decisions.
What Is PMYB&ALS?
PMYB&ALS is a federal, government-backed financing programme designed to:
1. Turn “job seekers” into “job creators” by making startup capital accessible without heavy collateral requirements.
2. Support small and medium enterprises (SMEs), freelancers, and IT/e-commerce businesses.
3. Strengthen the agriculture sector by financing crop and non-crop activities, including livestock, poultry, dairy, and fishery.
4. Promote financial inclusion for women and, in many categories, transgender applicants.
5. Reduce reliance on informal or high-interest lending.
Applications are submitted entirely online through the official portal and then routed to a partner bank in the applicant’s district for verification, document collection, and final disbursement.
Loan Tiers and Markup Rates:
The scheme is structured into three tiers, so applicants can choose an amount that matches the size of their business or farm:
Tiers:
1. Loan Amount (approx.)
2. Markup Rate
3. Best For
Tier 1:
=> Up to Rs. 500,000
=> 0% (interest-free)
=> First-time entrepreneurs, micro-businesses, small farmers
Tier 2:
=> Rs. 500,001 – Rs. 1,500,000
=> Around 5% per year
=> Growing small businesses
=> Small-to-mid agriculture operations
Tier 3:
=> Rs. 1,500,001 – up to Rs. 7,500,000
=> Around 7% per year
=> Established SMEs
=> large-scale agriculture, industrial/machinery financing
Notes:
Tier 1:
=> Generally requires no collateral, making it the easiest entry point for new applicants.
Tier 2 and Tier 3:
=> Typically come with a grace period (often up to 6 months) before principal repayment begins, though markup may accrue from the start.
Most first-time applicants are encouraged to begin with Tier 1 and move up in a future application once they’ve built a repayment track record. Exact figures can be revised by the government, so confirm current tier limits and markup rates on the official portal before applying.
Eligibility Criteria:
While specific requirements can vary slightly by bank and business category, the general eligibility rules are:
1. Nationality:
=> Must be a Pakistani citizen holding a valid CNIC or SNIC (resident Pakistanis only — overseas applicants are generally not eligible).
2. Age:
=> General category: 21 to 45 years.
3. IT & E-commerce category:
=> Relaxed to as low as 18 years in some cases (usually requires at least Matriculation/equivalent).
4. Gender:
=> Open to men, women, and transgender individuals, a dedicated quota is typically reserved for women applicants.
5. Employment status:
=> Government employees are usually not eligible.
6. Business status:
=> Both brand-new startups and existing businesses/farms can apply.
7.Education:
=> No strict minimum qualification is required for most categories, though relevant education or training can strengthen your application.
8. Business plan:
=> A clear business idea, feasibility outline, or agriculture plan is expected, especially for Tier 2 and Tier 3.
Required Documents:
Prepare clear, legible scanned copies (JPG or PDF) of the following before starting your application:
1. Valid CNIC (front and back).
2. Recent passport-size photograph.
3. Mobile number registered on your own CNIC (used for OTP verification).
4. Valid email address.
5. National Tax Number (NTN) from FBR, where applicable.
6. Business plan or feasibility study (especially important for Tier 2 and Tier 3).
7. Proof of business address (recent, usually within the last 3 months) for existing businesses.
8. Educational certificates/degrees, if available.
9. For agriculture applicants: land ownership documents or tenancy agreement.
10. Bank account details for disbursement.
=> Double-check that every document is current, clear, and correctly named before uploading blurred or outdated documents are one of the most common causes of delay.
Step-by-Step: How to Apply Online:
The entire application is submitted online no physical or paper applications are accepted.
Step 1: Visit the Official Portal:
=> Go to the official website: www.pmybals.pmyp.gov.pk. (accessible also via the main PMYP site, pmyp.gov.pk). This is the only authentic portal for registration be cautious of look-alike or third party sites asking for fees.
Step 2: Create Your Account:
=> Click “Apply Now” / “New Applicant”.
=> Enter your 13-digit CNIC number and CNIC issue date.
=> Verify your identity through NADRA verification.
=> Enter and verify your mobile number via OTP (must be registered on your own CNIC).
=> Provide a valid email address and set a secure password.
Step 3: Select Your Loan Tier and Category:
=> Choose Tier 1, 2, or 3 based on your funding need, and select whether you’re applying under the business or agriculture category (and sub-sector, e.g: IT, livestock, retail, manufacturing).
Step 4: Fill Out the Application Form:
Enter accurate details including:
=> Personal information (name, father’s name, date of birth, address).
=> Educational background.
=> Business/agriculture details and sector.
=> Requested loan amount and purpose.
=> Financial details, if you have an existing business.
Be thorough and honest inaccurate or incomplete information is a common reason for rejection or delay.
Step 5: Upload Required Documents:
=> Attach all the documents listed above in the correct format. Ensure scans are clear and complete.
Step 6: Submit and Save Your Application ID:
Once submitted, you will receive an Application/Reference ID via SMS and email. Save this you’ll need it to track your status.
Step 7: Bank Verification (Offline Stage):
Within roughly 7–15 working days, your application is forwarded to a partner bank in your district, which will contact you to schedule a branch visit. At the branch, you may need to:
=> Present your original CNIC and documents
=> Discuss and finalize your business plan
=> Complete any bank-specific formalities (loan agreement, guarantor details for higher tiers, etc.)
Step 8: Approval and Disbursement:
Once the bank completes its assessment, approved loans are disbursed as per the bank’s process often directly into your linked bank account, sometimes in tranches for larger, Tier 3 loans.
How to Track Your Application Status:
=> Log in to “pmybals.pmyp.gov.pk” using your CNIC and reference/application number.
=> The portal will show your current status: under review, forwarded to bank, approved, or requiring additional documents.
=> If your status shows “forwarded to bank” but you haven’t been contacted, reach out to the bank directly or use the official helpline.
Partner Banks:
The scheme is implemented through 15+ partner banks, including commercial, Islamic, and microfinance institutions such as:
=> National Bank of Pakistan (NBP)
=> Habib Bank Limited (HBL)
=> MCB Bank
=> Bank Alfalah
=> United Bank Limited (UBL)
=> Bank of Punjab
=> First Women Bank
=> Zarai Taraqiati Bank Limited (ZTBL) especially relevant for agriculture loans.
=> Several other commercial and Islamic banking partners.
You typically don’t choose your bank directly during online registration your application is routed to a partner bank in your district based on your location and sector.
Tips to Improve Your Approval Chances:
=> Start with Tier 1 if you’re a first-time applicant with limited credit history.
=> Write a clear, realistic business plan vague or overly ambitious proposals are more likely to be scrutinized or rejected.
=> Use your own CNIC-registered SIM to avoid OTP and verification failures.
=> Keep documents updated and legible this is one of the most common causes of delay.
=> Respond quickly when the bank contacts you for the branch visit.
=> Avoid third-party “agents” who claim they can speed up approval for a fee this is not an official process and is commonly associated with fraud.
Frequently Asked Questions:
1. Is this loan really interest-free?
Tier 1 loans (up to Rs. 500,000) are typically offered at 0% markup. Tier 2 and Tier 3 carry a subsidized markup, generally lower than standard commercial loan rates.
2. Can overseas Pakistanis apply?
No, the scheme is generally restricted to resident Pakistanis.
3. Can government employees apply?
No, government employees are typically not eligible under this scheme.
4. Is a minimum educational qualification required?
There’s generally no strict minimum requirement, though relevant education can be a favorable factor in the bank’s decision.
5. Is there a fee to apply?
No, the application itself is free. Be wary of anyone asking for payment to “process” or “guarantee” your application.
6. How long does the process take?
It can vary, but many applicants report the online stage taking under an hour, with the full process from submission to bank disbursement often taking anywhere from a few weeks to a couple of months depending on document readiness and bank workload.
Final Word:
=> The PM Youth Business and Agriculture Loan Scheme remains one of the most accessible government financing options for young entrepreneurs and farmers in Pakistan. Because exact loan limits, markup rates, and portal details are periodically revised by the government, always verify the latest figures directly on pmybals.pmyp.gov.pk before applying, and rely only on official channels for your application and status tracking.
=> This article is for general informational purposes and reflects publicly available information as of 2026. It is not official government content for authoritative and up-to-date details, always refer to the official PMYP/PMYB&ALS portal.